Thursday, June 23, 2011

Shahid Afridi

 Shahid Afridi Biography
Sahibzada Mohammad Shahid Khan Afridi was born on 1 March 1980 in Khyber Agency of the Federally Administered Tribal Areas, Pakistan, popularly known as Shahid Afridi, is a Pakistani cricketer and current One Day International (ODI) and Twenty20 captain of the Pakistani national team in the international circuit. He made his ODI debut on 2 October 1996 against Kenya and his Test debut on 22 October 1998 against Australia.

Afridi is from the Afridi tribe of the Khyber Agency in the Federally Administered Tribal Areas and hails from a Pashtun family. He is married and has two daughters, Aqsa and Ansha.

He is known for his aggressive batting style, and holds the record for the fastest ODI century which he made in his first international innings, as well as scoring 32 runs in a single over, the second highest scoring over ever in an ODI. He also holds the distinction of having hit the most number of sixes in the history of ODI cricket. Afridi considers himself a better bowler than batsman, and has taken 48 Test wickets and over 300 in ODIs. Currently Afridi is the leading wicket taker in the Twenty20 format taking 53 wickets from 41 matches.

In June 2009 Afridi took over the Twenty20 captaincy from Younus Khan, and was later appointed ODI captain for the 2010 Asia Cup. In his first match as ODI captain against Sri Lanka he scored a century however Pakistan still lost by 16 runs. He then also took over the Test captaincy but resigned after one match in charge citing lack of form and ability to play Test cricket; at the same time he announced his retirement from Tests. He retained the captaincy in limited-overs form of the game and led the team in the 2011 World Cup.

His general style of batting is very aggressive and attack oriented and has earned him the nickname “Boom Boom Afridi”. Moreover, out of the six fastest ODI centuries of all time, Afridi has produced three of them. As of 27 February 2011, he has an ODI strike rate of 113.83 runs per 100 balls, the third highest in the game’s history. This attitude has been transferred to Test cricket as well, with Afridi scoring at a relatively high strike rate of 86.13. He has an approach to batting that can change the tempo of a game and inspire the mood of an audience, as shown when a mass exodus of spectators occurred in Pakistan in late 2005 following his dismissal from the crease.

Having started as a fast bowler, Afridi decided to start bowling spin after someone told him he was throwing. He modelled himself on Pakistan leg-spinner Abdul Qadir. Afridi began his career as primarily a bowler, however after scoring the fastest century in his maiden ODI innings more was expected of him with the bat. He considers himself a better bowler than batsman. While he is renowned for his aggressive batting, he is also a handy leg-spinner capable of producing a good mix of wicket taking balls.

He has over 300 International wickets, most of which are from the ODI format. While his stock ball is the leg break, his armoury also includes the conventional off break and a ‘quicker one’ which he can deliver in the style of a medium-pacer. He bowls at a high speed for a spinner, resulting in lesser turn, and relying more on variations in speed. He occasionally sends down a bouncer to a batsman, which is very rare for a spin bowler.
 Shahid Afridi
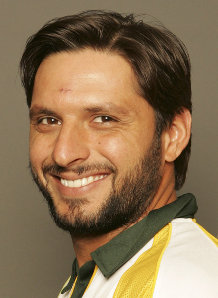
 Shahid Afridi
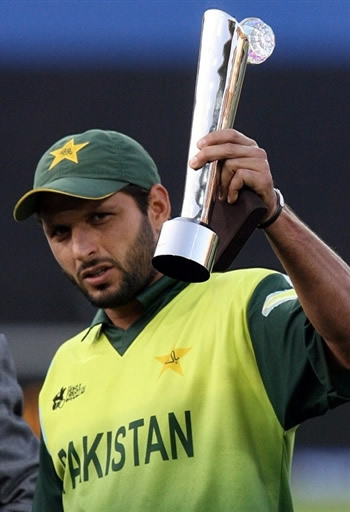
 Shahid Afridi

 Shahid Afridi

 Shahid Afridi   
Shahid Afridi Interview 1998 Anwar Maqsood

Saturday, May 14, 2011

Information about Whole Life Insurance


This blog post is about Whole Life Insurance.
Purchasing low cost life insurance doesn't need to be a grueling experience. Our site will help you understand the most common terms to determine what is best for you. Then, while you're here, please feel free to use our online service to find your best life insurance rates and quotes.

General Life Insurance Terms

Term Life: "Cheap" term life insurance is often purchased because It is the least expensive of all types of policies and comes in some variations including modified, graded, and decreasing. Decreasing term is generally the cheapest of all because the face value decreases over time while your premium remains level. This is generally purchased as a conversion or as mortgage life insurance.

The most common term life policy is “level term” meaning your face value and premium will be unchanged for the initial period of the term. The policy may say something like “renewable to age 95,” but contrary to what folks sometimes are led to believe, that does not mean your premium will stay the same. Term life premiums can increase substantially at the end of the initial term.

Term life comes with a variety of riders, but has no cash value, so you can’t borrow against it or cash surrender it. If you stop paying premium, you simply lose it.

It is possible to convert a term policy to anything else that the same company offers. If the company only offers term, your conversion will be to "annual renewable." For this reason you should purchase term from a company that also offers universal or whole life. When you convert, your premium will be adjusted to your age at that time. It may actually be less expensive to purchase a new policy from a different company, but if you have developed health problems, that may not be an option.

Level term life has its drawbacks, but is suitable for people who have reason to believe that they will not need life insurance as they get older. It could be used to insure a family business or to provide for education for children in the event of the death of the primary wage earner. It’s difficult to know for sure exactly what a person will need 20 or 30 years into the future, but a person who plans to pre-pay final expenses and who does not have an estate large enough to be effected by estate taxes probably will not need a large policy once the family has grown and the home mortgage has been paid. Remember, however, that life insurance also provides for a spouse, creates a legacy for loved ones, and simply makes things a lot easier for those who are left behind.

Permanent Life / Whole Life
A form of permanent life insurance will give you the most security for the longest time period—your whole life if set up properly. The easiest understood form of permanent life is Whole Life insurance. This simply provides you with a set face value and a set premium (called “level”) for your whole life, and if purchased while you are young, it can be quite low cost. It builds cash value, giving you a source of emergency funds as well as a surrender value if you decide later on that you no longer need it. The premiums are the more expensive than term, but far less than trying to renew a term or temporary policy after you have had one 20 years. As long as you don’t purchase a “modified” whole life, your premium will never change. A whole life policy also has riders available so you can cover your entire family or purchase disability options, unemployment waivers, and more.

Permanent Life  / Universal Life
Although it is more confusing to explain and can be unsatisfactory if not set up by a knowledgeable agent, Universal Life is the form of permanent life insurance with the most and best options. The premium goes into a savings account first, where it earns interest. Each month the cost of insurance and fees are deducted to pay for the universal life insurance policy which is in a separate account.  Because of this arrangement, the policy is flexible, meaning you can change your premium and your face value. Once you have some cash built up, you can also make withdrawals. If you never touch the savings portion, you can have enough in it after 20 years or so that the policy will begin to pay for itself, allowing you to reduce or eliminate your premium. The mistake that some people make which causes confusion about the universal life is in the initial funding. The policy will have a minimum premium which is just enough to pay the COI and fees for the first few years, sometimes as long as 15 years. Agents who are eager to gain clients by offering the “cheapest” premium, and who do not understand how a universal works, are apt to offer you a policy with a minimum or slightly higher premium. This may be a mistake as your savings account will not be able to build up and thus the policy will not be funded properly in later years.

If set up properly, the Universal Life is actually your most reasonably priced option with many companies. Then only two things could affect the future premiums. First the company could increase the costs of insurance to the highest allowable rates; no company would ever do this because they would lose many of their clients. Second, the interest rates paid on the savings portion could drop. This is not always in the company’s control, but even if rates go down, there will always be a floor below which they cannot go. Furthermore, each year, you receive a statement showing what your rate is and how your cash is building. A quick glance or a brief review by your agent will give you the assurance you need that your policy has remained stable and unchanged. If interest rates did drop, and you noticed that your cash was starting to decrease, a premium increase of just a few dollars would keep it growing.

Some other Types of Policies

No-Load
In today’s market place, nearly everything we use is purchased through a chain of individuals. In some places it is still possible to buy milk directly from the farmer, and you can go online and purchase your new car directly from the manufacturer—if you can find one. You will save dollars, but don’t expect the dealership to be real cooperative in backing up a warranty on a car they were not permitted to sell.

Insurance is similar. You can find “no-load” policies, meaning you do not deal with an agent. Generally such policies are purchased through the mail, and you are totally responsible for understanding the terms. Some companies may use agents, but you will be responsible for paying the agent directly, thus lowering your premium as the agent’s commission will not be factored into it. Be aware, however, that such policies may appear cheaper, but are usually not what you thought you were purchasing. No load is possible, but is not always the best way to purchase life insurance.

Joint Life
Only a few companies offer this variation, available either as whole life or term, but it is worth mentioning as it can save a significant amount of money and be an option when one person has pre-existing health conditions. Joint life insures two or more people on one policy and for one premium that is more than it would be for the youngest person, but less than it would be for the oldest. The policy can be set up as first to die or second (last) to die (also known as “survivor”) option. The “first to die” pays when the first person on the policy dies and provides a survivor with an income. The survivor or second to die option assumes that the money will not be needed until the last person on the policy dies. Then it provides heirs with a legacy. This variation provides a great tax free way to pay estate taxes.

Company Ratings
Company ratings are assumed to provide information about the financial stability of the company as well as facts about the claim paying history. Some of the best known sources are A.M. Best or Standard & Poor's.

Additionally, a newer source is Street.com. Ratings from this company are paid for by the citizens or people on the street. Regardless of ratings, however, it is truly a good idea to talk to your friends and business colleagues, and to check the Better Business Bureau for complaints against a company you may be considering. This information will often be more reliable than a formal rating.


Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
 Information about Whole Life Insurance
Information about Whole Life Insurance

New York LASIK Information Just for You.


This blog post is about New York LASIK.
New York LASIK Specialist
Dr Gregory Pamel is a fellowship trained corneal specialist who has helped thousands of New York LASIK and cataract surgery patients to obtain better vision. He performs a wide range of vision correction procedures at his Upper Eastside Manhattan LASIK center. Dr. Gregory Pamel has had more than 15 years experience in the:

LASIK
PRK/LASEK
Cataract and Lens Implant Surgery
Multifocal Lens Implants
Crystalens® Lens Implants
Implantable Contact Lens
Corneal Transplants
Keratoconus
Ectasia
Corneal Collagen Crosslinking
Gregory J. Pamel, M.D. Selected by Premier Surgeon as One of the Leading Innovators in Premium Intraocular Lens Surgery
The PS250 is a list of 250 surgeons the publisher and editors of Premier Surgeon have identified as leading innovators in the field of cataract and premium intraocular lens implant surgery. Click here to read more about this distinctive group.

Gregory J. Pamel, M.D. Selected to Be Principal Investigator for FDA Clinical Trial on Corneal Collagen Crosslinking for the Treatment of Keratoconus and Post-LASIK Ectasia
Gregory J. Pamel, MD, has been selected to be principal investigator for an FDA clinical trial to evaluate the safety and efficacy of corneal collagen crosslinking for keratoconus and ectasia. Dr. Pamel was one of 10 physicians selected in the U.S. to participate in the trial sponsored by Topcon Medical Systems, Inc. using the VEGA UV-A Illumination System. Dr. Pamel was the first physician in the FDA trial to perform the procedure on patients in July 2010. To learn more about keratoconus, ectasia and corneal collagen crosslinking, please click here.

The Most Advanced Bladeless-All Laser Lasik- Technology Available
Dr. Pamel is the first doctor in New York to utilize the most advanced bladeless, all-laser, LASIK system called Z LASIK®. Developed by the Ziemer Group in Switzerland, this femtosecond technology is the fastest and most accurate bladeless technology available. Dr. Pamel is committed to providing his patients the most advanced laser technology to achieve the best outcomes after LASIK.

Dr. Pamel was featured in the New York Times Magazine Super Doctors issue in 2009, 2010 and 2011. Ballots were sent out to thousands of doctors asking: "if you needed medical care, which doctor would you choose?" Those doctors "most highly regarded by their peers" were chosen to be part of the Super Doctors Issue. According to the publication, "numerous safeguards are in place to prevent ballot manipulation and doctors may not self nominate".

Dr. Pamel was awarded the American Academy of Ophthalmology Achievement Award in November 2008 in which he was recognized for his contribution to the scientific programs of the Annual American Academy of Ophthalmology Meeting. 

Gregory J. Pamel, M.D. is pleased to announce the merger of his practice with the practice of Dr. Calvin Roberts.
Dr. Roberts is a specialist in cataract, corneal and LASIK surgery with an international reputation in the field of eye surgery. After 25 years of practice, Dr. Roberts has decided to devote his full attention to his research interests in ophthalmology. "I spent considerable time deciding who the best person would be to take over my practice and I am certain I have found the right person in Dr. Pamel" said Dr. Roberts. Recently Dr. Roberts was honored by New York Magazine in its Best Doctors of New York Issue as one of the top cataract surgeons in the New York Metro Area. "I have the highest confidence in Dr. Pamel's surgical skills as a cataract, corneal and lasik surgeon." Said Dr. Roberts.
While there are many eye doctors in New York State, not all offer laser vision correction. Many eye doctors in New York treat vision disorders such as glaucoma, cataracts, macular degeneration and other eye diseases. Only skilled ophthalmologists that have experience treating refractive errors perform LASIK in NY. LASIK surgery is very safe, and is one of the most effective eye surgeries performed in New York State.

We offer people a way to find a doctor for LASIK eye surgery in New York by placing many skilled LASIK surgeons in New York in one website. Furthermore, we can help patients find laser eye surgery in NY at an affordable cost and provide financing for their procedure.

Over the past several years there has been an increase in laser eye surgery procedures performed in New York. Increasing levels of technology and demand, coupled with declining equipment and laser costs have helped the popularity of laser eye surgery in New York increase steadily. Nationally, about 1.5 million LASIK surgeries are expected to be performed in 2001, with a substantial portion of them in New York.
New York LASIK Information
 New York LASIK Information
 New York LASIK Information
 New York LASIK Information
 New York LASIK Information
 New York LASIK Information
 New York LASIK Information
 New York LASIK Information
 New York LASIK Information
New York LASIK Information

Home Equity Loans Information Just for You


This blog post is about Home Equity Loans.
Home equity loans allow a homeowner to borrow money by pledging the house as collateral. Borrowers who want to borrow a relatively large amount of money or who don’t have good credit often find the home equity loan to be attractive.
A home equity loan is a type of second mortgage, not to be confused with a home equity line of credit.
Lenders may be more liberal because they view home equity loans as relatively safe. You can’t disappear with your house or hide it if you default on your loan, so the lender has a good chance of collecting the collateral. Also, you are likely to make your payments a priority if your home is on the line.
Advantages of Home Equity Loans

Home equity loans are attractive to borrowers for a few main reasons:

They typically have a lower interest rate (or APR)
They are easier to qualify for if you have bad credit
Payments on a home equity loan may be tax deductible
Borrowers can get relatively large loans with this type of loan
Common Home Equity Loan Uses

Borrowers use home equity loans for some of life’s larger expenses, because homes tend to have a lot of value to borrow against. For example, you find that a lot of borrowers want to

Remodel or renovate the house
Pay for a family member’s college education
Finance the purchase of a second home
Consolidate high-interest debts
Pitfalls of Home Equity Loans

Before using a home equity loan for any purpose, you should be aware of the pitfalls of these loans. The main thing is that you can lose your home if you fail to meet the payment schedule required by the loan.

Another common pitfall of home equity loans is that scammers have found plenty of ways to cheat homeowners out of their most valuable asset. Be sure that you know who you’re doing business with. If something smells fishy (like a high-pressure sales pitch or an inability to put things in writing), then take a step back and make sure the deal is legitimate.

How to Find the Best Home Equity Loans

Finding the best home equity loan can save you thousands of dollars – at least. In order to get the best loan, I recommend that you:

Shop around. Try a variety of sources (banks, brokers, and credit unions)
Manage your credit score and make sure your credit reports are accurate
Ask your network of friends and family who they recommend
Compare your offers to those found on websites and advertisements
Additional Home Equity Loan Tips

To make the deal work out in your best interest, make sure that it is the right deal in the first place. Is a home equity loan a better fit for your needs than a simple credit card account? If you’re not sure, figure it out before you put your home at risk.

Plan out your budget ahead of time. Make sure that taking the loan will not overburden you.

Review and consider insurance to cover the payments if something happens. You may or may not need insurance. If you’re going to include it in your program, try to pay the premiums monthly – not up front.

Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
 Home Equity Loans Information
Home Equity Loans Information

What is mesothelioma and Information about Mesothelioma.


This blog post is about Mesothelioma.
What is Mesothelioma?
Mesothelioma is a cancerous disease that is becoming more and more common. Affecting the mesothelial cells that make up the mesothelium – the outer lining that protects the body’s major organs such as the heart, stomach and lungs – this form of cancer is a direct result of regular and unprotected exposure to asbestos. The symptoms and the latency period of this disease mean that it is difficult to diagnose. Treatment for mesothelioma is still being investigated through clinical trials and research, but as a rule it responds poorly to the treatments that are currently used.


The people most at risk from being carriers of this cancer are those have worked with asbestos over the past thirty to fifty years. Because of this, the disease is most common in men between the ages of sixty and seventy as this is the group that commonly worked with asbestos during those years. Because of the lack of protection and regulations in those days, these workers were constantly exposed to the dust and fibres from the asbestos, which caused the cells of the mesothelium to become abnormal. However, because the disease takes decades to develop fully and manifest, many of them were oblivious to this until thirty to fifty years later. It is these men who are now lodging multi-million dollar lawsuits against the unscrupulous companies that exposed them to the dangers of asbestos, even though they were aware that it could cause harm to the employees.


There are also other people at risk from the disease; namely those who have had regular contact with a person who has worked with asbestos. Because these workers regularly carried dust and fibres on their clothes, skin and in their hair, they fibres and dust could be ingested by family members, who were then at risk of developing mesothelioma, respiratory problems or another asbestos related disease.


The organs most affected by mesothelioma are the lungs and the surrounding tissue. Pleural mesothelioma, which is the type affecting the lining of the lungs, is the most common variation of this cancer with symptoms which include breathing and swallowing difficulties, coughing, shortness of breath, fever and weight loss. The abdomen is another area affected by this cancer, and this variation is known as peritoneal mesothelioma. This type of mesothelioma is not as common as pleural mesothelioma. Symptoms of peritoneal mesothelioma can include nausea and vomiting, weight loss and loss of appetite, fever, bowel obstruction and pain or swelling of the stomach area. The last variation of the cancer is pericardial mesothelioma, which is where the cancer affects the heart and the tissue surrounding it. This variation is a rare one, and symptoms can include palpitations, breathing difficulties, and persistent coughing.


The symptoms of mesothelioma are very common to a number of other diseases which are more well-known in society. Therefore, it is not unusual for the patient to be misdiagnosed when he or she goes in displaying any or all of these symptoms. People who have worked with asbestos should always let their doctor know this so that the doctor is more aware and more conscious of the possibilities in the event that the symptoms do manifest. A speedy diagnosis is important to the effective treatment of mesothelioma, and without being aware of the facts your doctor may not be able to make the diagnosis as quickly as he would if he is aware of the situation.


Although there are treatments for mesothelioma, they do not have a high success rate particularly on patients in whom the cancer is in its later stages. The faster the mesothelioma is diagnosed and treated, the more chance of success, which is why it is important to get as fast a diagnosis as possible.


Current treatments for mesothelioma include surgery, radiation therapy, palliative therapy and chemotherapy. The National Institute of Cancer along with a variety of other organizations and sponsors are currently conducting research into mesothelioma and carrying out clinical trials to try and find a treatment that will not only be more effective but will enable the successful treatment of the disease even in its later stages.


Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
 Information about  Mesothelioma.
Information about  Mesothelioma.

Miami, Florida, Personal Injury Attorney Information For You


South Florida Accident Attorney Helping the Injured in Miami, Palm Beach, Boca Raton and Fort Lauderdale
The Miami personal injury attorneys of Greenberg & Stone, P.A., have an ongoing pledge to honesty, integrity, professionalism and community service. Over our decades of legal practice, Greenberg & Stone has established itself as a personal injury law firm built on a foundation of strong dedication to our clients.

With offices in Miami, Broward, Palm Beach, Tampa, Orlando and Pensacola, the AV-rated* law firm of Greenberg & Stone provides effective and ethical legal counsel to injured persons throughout Florida. Partners Stewart G. Greenberg and Mark D. Stone offer more than 60 years of experience litigating personal injury cases in Florida and across the nation. We are joined by attorney Linda Luce, who is of counsel to the firm and offers legal services in family law.

Our Past Cases Illustrate Our Commitment to Justice and Fairness for Injured People
Our Miami personal injury attorneys continually strive for justice and fairness in the form of compensation for the victims of accidents caused by negligence or intentional wrongdoing by others. Our trial lawyers have obtained many substantial verdicts and settlements in excess of one million dollars, including one case we settled for $22 million. Our Florida injury lawyers have the experience necessary to get the results you need and deserve.

Demonstrated Experience With a Wide Range of Injury Cases
A car accident is different from medical malpractice, which is different from an accident on board a cruise ship. At Greenberg & Stone, our Miami personal injury lawyers have first-hand experience with a wide range of injury and accident lawsuits:

Motor vehicle accident claims
Premises liability lawsuits
Defective product cases
Cruise ship accident and injury claims
Amusement park accident cases
Medical malpractice lawsuits
Pharmacy negligence claims
Airplane crash lawsuits
Wrongful death suits
Don't Face the Future Alone After a Major Accident:
Call (855) 874-6366 for a Free Consultation
Injuries change lives. You should not have to face the consequences of a major accident alone. As you learn more about Greenberg & Stone, you will discover that we can provide the compassionate and competent legal counsel you deserve. It would be our honor and privilege to represent you, as we have for thousands of other injured persons in Florida.

We stand with our clients, side-by-side, through every phase of the legal process, working on a contingency fee basis, only taking a portion of the recovery if there is one. This means that we shoulder the financial risk of pursuing legal justice for our injured clients. If you do not receive financial compensation, we do not get paid. Read more about contingency fee agreements.

Let Greenberg & Stone fight for you. Our attorneys are available 24/7 through e-mail or answering service. Call (855) 874-6366 or contact us online to find out how our client-oriented and individualized approach can work for you. We always have a Spanish-speaking member of staff available.

* AV Preeminent and BV Distinguished are certification marks of Reed Elsevier Properties Inc., used in accordance with the Martindale-Hubbell certification procedures, standards and policies. Martindale-Hubbell is the facilitator of a peer review rating process. Ratings reflect the confidential opinions of members of the Bar and the judiciary. Martindale-Hubbell ratings fall into two categories — legal ability and general ethical standards.

Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
 Miami, Florida, Personal Injury Attorney Information For You
Miami, Florida, Personal Injury Attorney Information For You

 
Design by Free WordPress Themes | Bloggerized by Lasantha - Premium Blogger Themes | Blogger Templates